SSNIT contributions explained: Tier 1, Tier 2, Tier 3 and your pension (2026)
Every month 18.5% of your basic salary goes into your pension, 5.5% from you and 13% from your employer. Here's where each cedi goes, and how SSNIT works out the pension you'll get.
If you work for an employer in Ghana, 18.5% of your basic salary goes towards your pension every month. 5.5% is deducted from your pay, and your employer adds 13% on top. Most of that money, 13.5% of your salary, goes to SSNIT (Tier 1). The other 5% goes to a private pension scheme your employer chooses (Tier 2). On top of that you can choose to save more in a voluntary Tier 3 fund, and the government gives you tax relief for it.
It's one of the biggest deductions on a payslip and one of the least understood. This guide explains where the money goes, what it earns you, and how to check it. To see the figures for your own salary, use the PAYE and salary calculator. To estimate your pension, use the SSNIT pension calculator.
The three tiers
Ghana's pension system, set up by the National Pensions Act, 2008 (Act 766), has three tiers:
| Tier | What it is | Who runs it | How much goes in |
|---|---|---|---|
| Tier 1 | The basic national social security scheme, which pays a monthly pension for life | SSNIT | 13.5% of basic salary |
| Tier 2 | An occupational scheme, paid out as a lump sum when you retire | Private trustees chosen by your employer | 5% of basic salary |
| Tier 3 | Voluntary provident fund or personal pension | Private trustees | Whatever you and your employer choose |
Tiers 1 and 2 together make up the compulsory 18.5%. Tier 3 is extra and optional.
One detail surprises people. Out of the 13.5% for Tier 1, 2.5 percentage points go to the National Health Insurance Fund, so SSNIT itself keeps 11% of your basic salary for your pension.
Where 18.5% of a GH₵5,000 salary goes
Take a basic salary of GH₵5,000 a month:
| Share of basic salary | Amount | |
|---|---|---|
| Deducted from your pay | 5.5% | GH₵275.00 |
| Paid by your employer on top | 13% | GH₵650.00 |
| Total contribution | 18.5% | GH₵925.00 |
| of which Tier 1 (to SSNIT, including NHIS) | 13.5% | GH₵675.00 |
| … NHIS's part of Tier 1 | 2.5% | GH₵125.00 |
| … SSNIT's pension part of Tier 1 | 11% | GH₵550.00 |
| of which Tier 2 (to your employer's scheme) | 5% | GH₵250.00 |
Your employer deducts your GH₵275 and pays the whole GH₵925, splitting it between SSNIT and the Tier 2 trustee. The 5.5% comes off before income tax, so you don't pay tax on it. With a GH₵5,000 basic salary, that saves you 25% of GH₵275 in tax. The PAYE guide walks through that calculation.

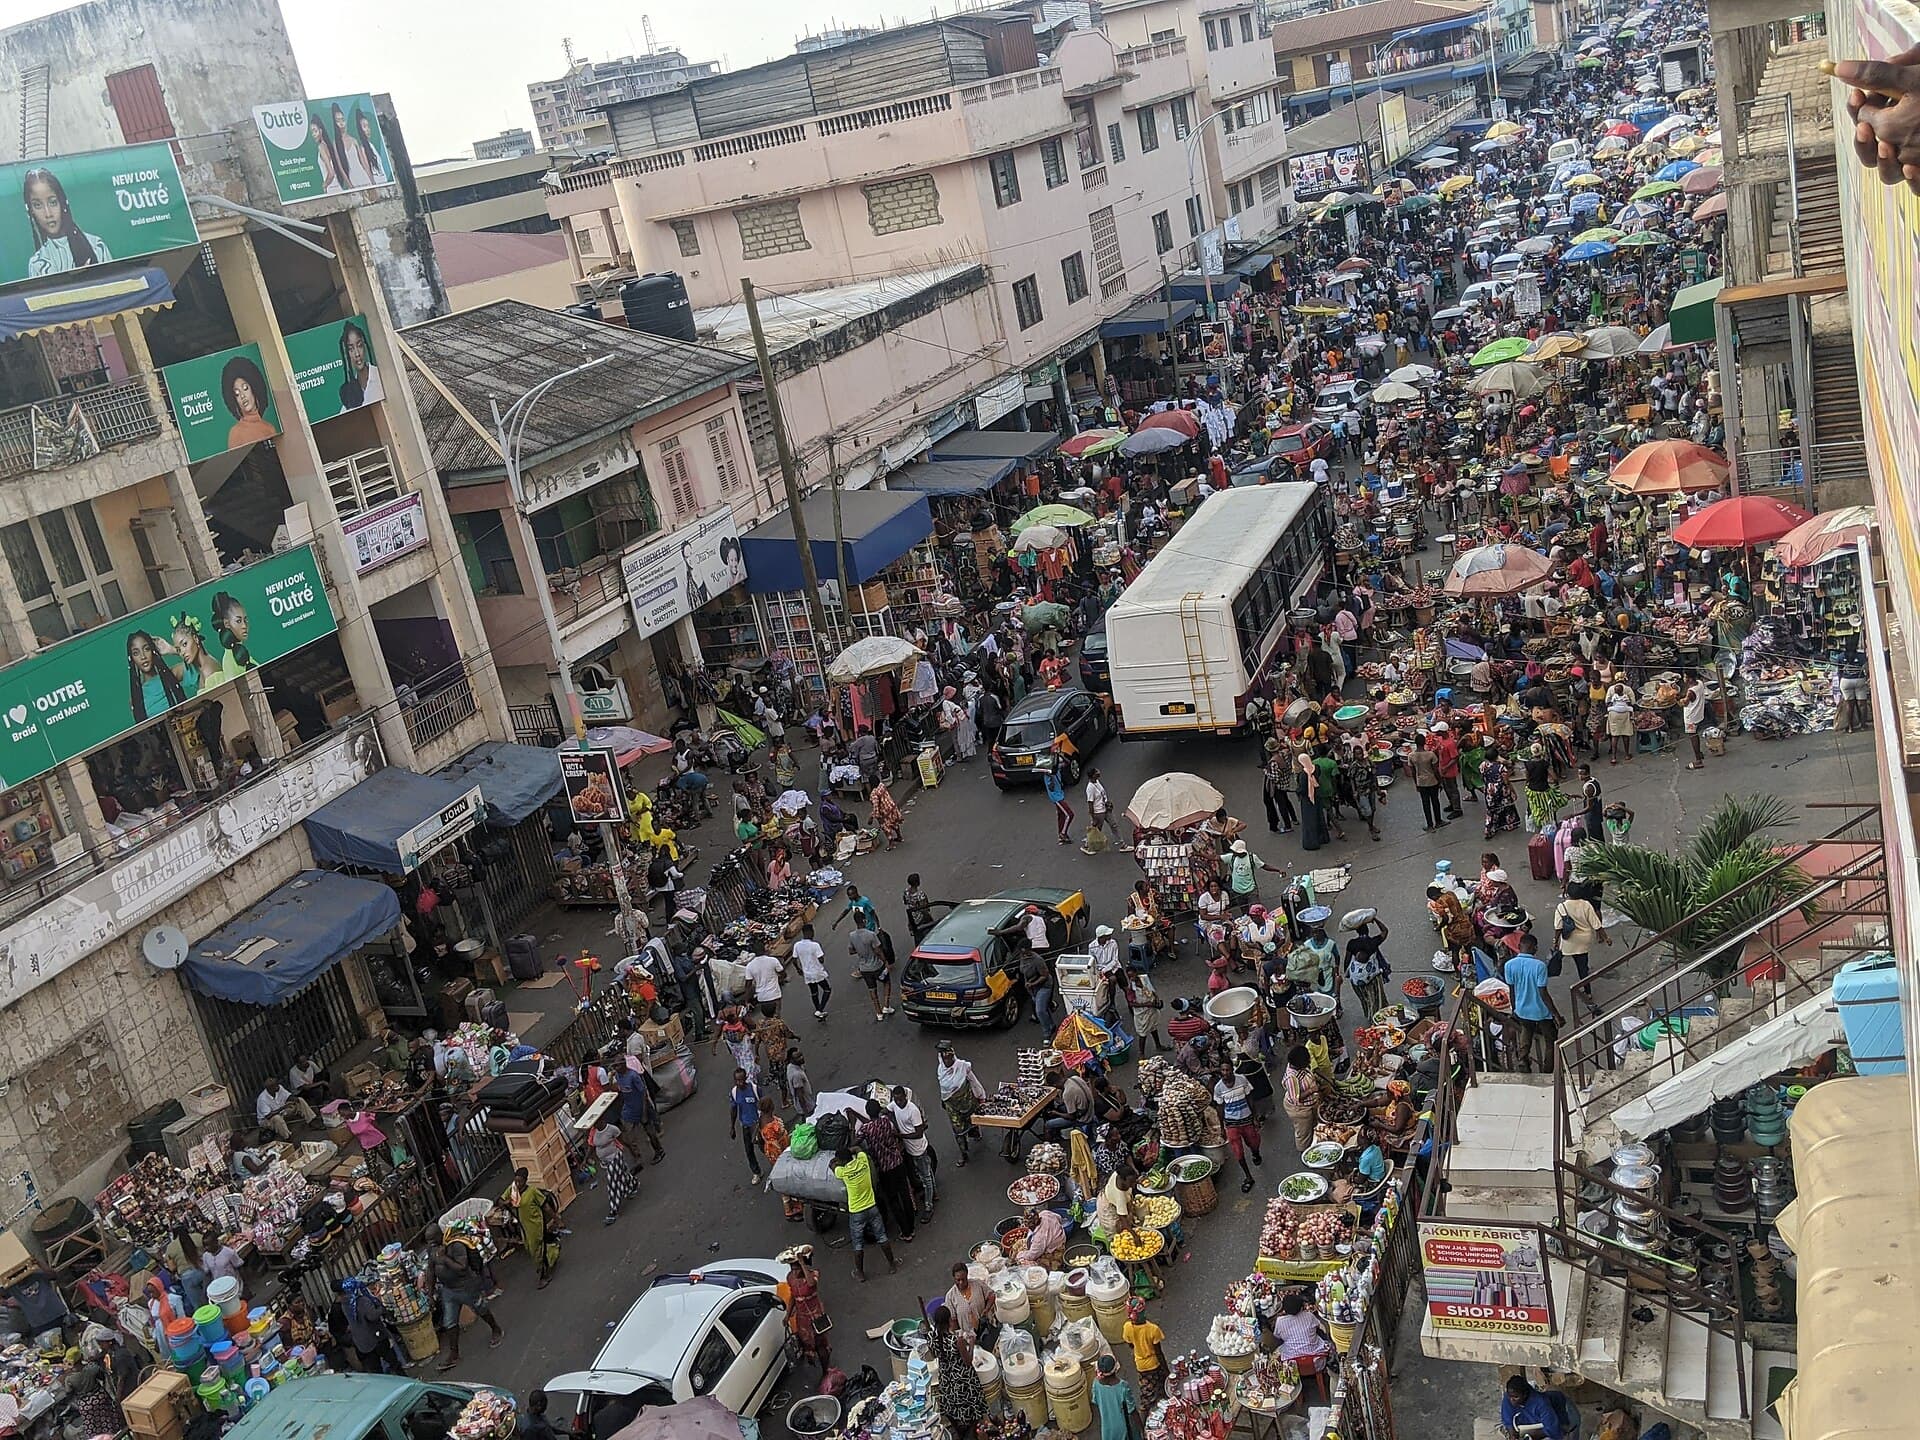
Accra Central. For most salaried workers, SSNIT is on every payslip. Photo: Muntaka Chasant, CC BY-SA 4.0, via Wikimedia Commons
Only basic salary counts, within limits
Contributions are charged on basic salary, not on allowances. A job paid GH₵5,000 basic plus GH₵3,000 in allowances contributes on GH₵5,000 only. That's cheaper for employer and employee today, but it also means the allowances do nothing for your pension.
SSNIT also sets a floor and a ceiling each year. For 2026:
- Minimum insurable earnings: GH₵587.80 a month. Contributions are paid on at least this much, even for someone paid less.
- Maximum insurable earnings: GH₵69,000 a month. Above that, no contributions are charged. On a basic salary of GH₵80,000, contributions are charged on GH₵69,000: GH₵3,795 from the employee and GH₵8,970 from the employer.
Tier 3: saving more, and paying less tax
Tier 3 is voluntary. You, your employer, or both can pay into a provident fund or personal pension. Contributions of up to 16.5% of basic salary are relieved from income tax. In practice that means they come off your chargeable income before PAYE is worked out.
For someone in the 25% tax band, every GH₵100 put into Tier 3 costs only GH₵75 in take-home pay, because GH₵25 would otherwise have gone to tax. It's the most straightforward legal tax saving most employees have. Rules on when you can withdraw, and what tax applies if you withdraw early, depend on the scheme, so read your scheme's rules before you sign up.
How your SSNIT pension is worked out
Your Tier 1 pension depends on two things: how long you contributed and your salary.
- You need at least 180 months (15 years) of contributions to get a monthly pension.
- Those first 180 months earn a pension right of 37.5%.
- Every further 12 months adds 1.125%, up to a maximum of 60%. That maximum is reached at 420 months, which is 35 years.
- Your monthly pension is that percentage of the average of your best three years' salaries.
- The full pension starts at 60. You can retire from 55 on a reduced pension. SSNIT applies an early-retirement reduction to your figure.
- In 2026 the minimum monthly pension for new pensioners is GH₵400.
Worked examples
These come from the same formula the SSNIT pension calculator uses:
| Years contributed | Average of best 3 years | Pension right | Monthly pension (from 60) |
|---|---|---|---|
| 15 years (180 months) | GH₵4,000 | 37.5% | GH₵1,500.00 |
| 20 years (240 months) | GH₵2,500 | 43.125% | GH₵1,078.13 |
| 25 years (300 months) | GH₵6,000 | 48.75% | GH₵2,925.00 |
| 30 years (360 months) | GH₵6,000 | 54.375% | GH₵3,262.50 |
| 35 years (420 months) | GH₵6,000 | 60% | GH₵3,600.00 |
| 40 years (480 months) | GH₵10,000 | 60% (the maximum) | GH₵6,000.00 |
Only complete years count. Someone with 185 months still has a 37.5% right, because the next 1.125% needs a full 12 extra months. And someone with 150 months, 30 short of 180, doesn't qualify for a monthly pension at all. If that's you, contact SSNIT about what you're due.
The lesson from the table is that the years matter. Going from 25 to 35 years of contributions raises the pension by almost a quarter on the same salary.

Tomatoes for sale in Tamale. Self-employed traders can contribute to SSNIT voluntarily. Photo: Ibn Shiraz, CC BY-SA 4.0, via Wikimedia Commons
If you're self-employed
Self-employed people aren't covered automatically, but they can register with SSNIT and contribute voluntarily towards a Tier 1 pension. If you run your own business, it's worth asking SSNIT at your nearest branch what you'd pay and what it would earn you.
Check that your contributions are being paid
Your employer deducts your 5.5%, but that doesn't prove the money reached SSNIT. It's worth checking your contribution record with SSNIT from time to time, for example through SSNIT's own channels or at a branch. Missing months are far easier to sort out while you're still with the employer than years later at retirement.
Common questions
What is the SSNIT contribution rate in 2026? 18.5% of basic salary: 5.5% from the employee and 13% from the employer. Of that, 13.5% goes to Tier 1 (SSNIT, including 2.5% for the NHIS) and 5% to Tier 2.
Is SSNIT deducted before income tax? Yes. Your 5.5% comes off before PAYE is calculated, so you don't pay tax on it. Tier 3 contributions up to 16.5% of basic salary are relieved too.
What's the difference between Tier 1 and Tier 2? Tier 1 is SSNIT's scheme and pays a monthly pension for life. Tier 2 is a private occupational scheme and pays a lump sum when you retire.
How many years do I need to contribute to get a pension? At least 15 years (180 months). That earns a pension of 37.5% of the average of your best three years' salaries, rising to 60% after 35 years.
Can I get my SSNIT money if I stop working before 60? The monthly pension is paid from 60, or on a reduced basis from 55. Other benefits exist for invalidity and for survivors. For your own case, ask SSNIT directly.
Do allowances count towards SSNIT? No. Contributions, and so your pension, are based on basic salary only, up to the GH₵69,000 monthly ceiling for 2026.
Last checked 27 September 2026 against SSNIT's old-age pension page, SSNIT's 2026 insurable earnings notice and the National Pensions Act, 2008 (Act 766). Rates change; the pension calculator always uses the current ones. This guide explains how the scheme works; SSNIT's own record decides your benefit.
Cover photo: JulianGrayscales, CC BY-SA 4.0, via Wikimedia Commons